

Dollarwise: Budget & Tracking
by HammerMedia
3.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.3
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
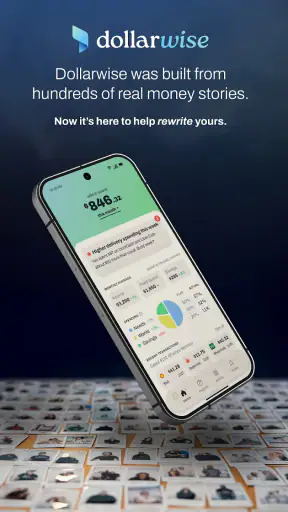
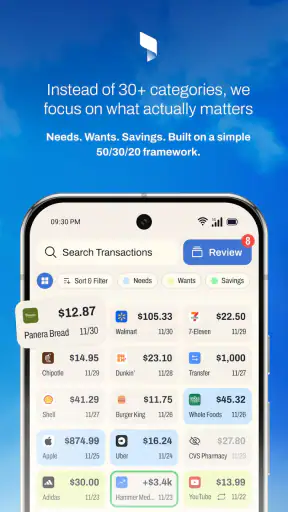
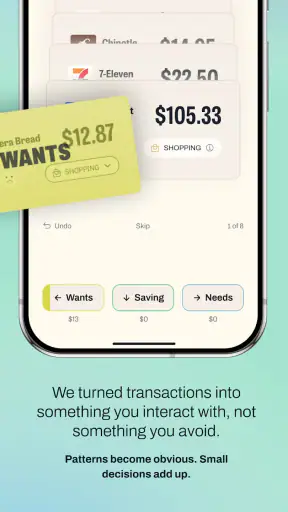
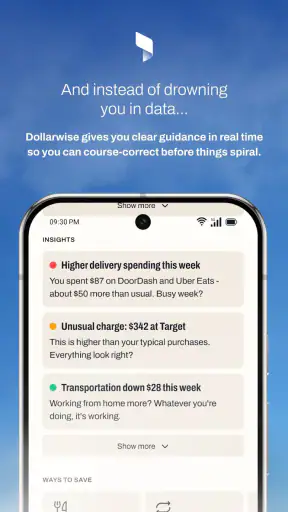
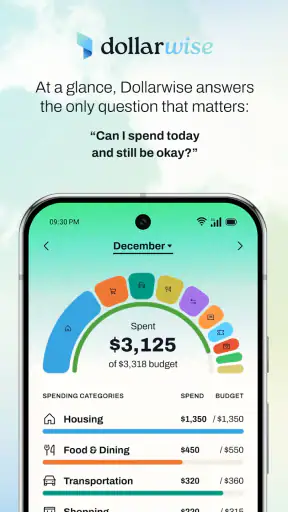
 Analysis by Getfullapps
I spent time with Dollarwise: Budget & Tracking as a personal finance app, using it with the kind of routine most people actually have: checking what has already been spent, thinking about upcoming bills, and trying to understand why the balance disappears faster than expected. Its central idea is simple, but the experience depends heavily on whether you are willing to keep your entries current. This is not a magic solution that fixes messy finances in the background. It is more useful as a place to build a repeatable money habit.
That distinction matters. Many finance apps promise a complete picture of your financial life, while a lightweight budgeting tool can be more practical when you want to stay involved in the process. Dollarwise is free to install, rated for Everyone, and developed by HammerMedia. It has reached over one hundred thousand installs, with an average rating of 3.3 from around two thousand ratings, so the public response is mixed rather than universally enthusiastic. I found that fair: the app can be approachable for everyday tracking, but it asks more from the user than a fully automated service.
Building a baseline workflow that you can actually maintain
The best way to start is not by trying to reconstruct every financial decision you have ever made. I would begin with one ordinary week. Record the purchases that normally get forgotten, such as a coffee on the way to work, a quick convenience-store stop, or a small digital purchase. Then add the larger predictable items that shape the month. This gives Dollarwise a useful starting point without turning the first session into an exhausting accounting project.
My preferred routine is to open the app at a fixed moment, rather than whenever I happen to remember. A short check after lunch or before bed is easier to repeat than a vague promise to “do it later.” The value comes from seeing patterns while they are still fresh. If I wait until the end of the month, small purchases blur together and I am more likely to guess, skip, or enter them in the wrong place.
For an everyday scenario, imagine someone paid on a Friday and feels comfortable for the first few days. By the following weekend, food, transport, and a couple of unplanned purchases have reduced the available money more than expected. A quick Dollarwise review can turn that feeling into a visible pattern. The important insight is not merely the total; it is noticing which type of spending repeatedly appears between payday and the next bill. That makes the next decision more concrete.
I would separate fixed obligations from flexible spending as early as possible. Rent, utilities, subscriptions, and loan payments behave differently from groceries, entertainment, or impulse purchases. Even if your personal categories are simple, this distinction helps you avoid treating money reserved for a bill as if it were available for casual spending. It also makes a monthly review more useful because you can tell whether the problem is an expensive obligation or a series of small choices.
One practical habit is to enter transactions close to the moment they happen, then use a weekly review for corrections. These are two different jobs. Immediate entry preserves accuracy, while the weekly pass catches duplicates, forgotten cash spending, or a purchase that was placed under the wrong category. Trying to perform both jobs only once a month creates unnecessary friction and makes the app feel more demanding than it needs to be.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
There is also a psychological benefit to keeping the first setup modest. If you create an elaborate structure before understanding your own spending, you may spend more time maintaining categories than learning from them. I would rather begin with a few meaningful groups and expand only when a distinction changes a decision. A category is useful when it helps me act differently, not simply because it makes the list look detailed.
Settings worth checking before the routine becomes automatic
Before relying on any finance app, I like to inspect its available settings rather than accepting the initial arrangement without thought. In Dollarwise, this is especially important because the usefulness of a manual tracker depends on how comfortable the entry process feels. Check the defaults for categories, dates, and any display or notification options that are available in your version. The goal is to reduce repeated taps and make the information easier to read, not to turn the app into a complicated project.
Date handling deserves particular attention. A purchase made late at night, a transaction entered the next morning, or a bill paid around a month boundary can distort a review if it lands in the wrong period. I make a point of checking the transaction date whenever an entry is added after the fact. This small correction prevents a surprisingly common mistake: thinking one month was unusually expensive when the real issue was that a few items were recorded in the neighboring period.
Category choices should reflect how you make decisions. Someone who wants to reduce restaurant spending needs a clear food distinction, while someone focused on commuting may get more value from separating transport costs. I would not copy a complicated category system from another person. Instead, I would ask which two or three spending areas I am most likely to change. Those are the categories that deserve the clearest labels.
Notifications, where available, should be treated as reminders rather than a substitute for attention. Too many prompts can become background noise, especially if they arrive at inconvenient times. A brief, predictable reminder is more useful than constant interruption. If you tend to ignore alerts, a calendar habit or a fixed daily checkpoint may work better than adding more notifications.
Privacy is another reason to understand the app’s role before entering sensitive information. I would use Dollarwise as a tracking and budgeting workspace, not assume that it replaces a bank’s secure account interface. Avoid treating a manually maintained record as proof that a payment has cleared. For important obligations, I would still verify the transaction through the relevant financial service. This two-step approach takes a little longer but avoids confusing a budget entry with an actual bank balance.
The app is free, but it includes in-app purchases ranging from around fifteen dollars to five hundred dollars per item. That is worth keeping in mind before committing to any paid option. I would first establish whether the free experience supports my basic routine and only then consider an upgrade. A finance tool should earn that decision through daily usefulness, not through pressure to unlock something before I know what problem it solves.
Faster patterns for people who dislike repetitive money admin
Experienced users do not necessarily enter more information; they create fewer decisions. I use a consistent naming and categorization approach so that familiar expenses can be recorded without stopping to rethink the structure. If the same type of purchase keeps moving between categories, that is a sign the categories are too specific or poorly defined. Simplifying them can make the whole workflow faster and more reliable.
A useful shortcut is to review spending in batches, but only when the batch is still manageable. For example, I might record several receipts together after grocery shopping, then immediately check that the total matches what I actually paid. This works better than collecting every receipt for weeks. The longer the delay, the more likely it becomes that a missing transaction will go unnoticed.
Recurring obligations also benefit from a repeatable pattern. I would make a short list of payments that appear every month and check them at the beginning of the period, then confirm them after they are paid. This avoids a common budgeting error: mentally counting a bill as handled simply because it is familiar. The app can show what I intended to track, but I still need to distinguish expected spending from completed spending.
Another effective pattern is a “decision review” rather than a purely numerical review. At the end of the week, I ask three questions: which purchase was planned, which was necessary but underestimated, and which was avoidable? The answers are more actionable than staring at a total. Dollarwise becomes more valuable when the entries lead to a change in next week’s behavior, such as bringing lunch, postponing a purchase, or setting aside bill money earlier.
I also recommend reviewing one category at a time when the month feels overwhelming. Looking at every expense at once can create a vague sense of failure. Focusing on transport, food, or leisure gives the review a narrower purpose. Once that area is understood, move to the next. This is a simple way to use the app as a decision aid instead of a source of guilt.
For couples or families, the limitation is that a manual tracker needs an agreed process. If only one person records shared spending, the picture may be incomplete. A workable arrangement might be a shared weekly check where both people confirm the entries that affect the household. If that cooperation is unlikely, an app built around automatic account synchronization may be a better fit, even if it offers less hands-on control.
Where the manual approach reaches its limits
Dollarwise is not the right choice for everyone. If you expect automatic importing from banks, investment monitoring, bill negotiation, credit analysis, or a complete household dashboard, you should compare it with a more comprehensive finance service before settling in. A manual budgeting app can encourage awareness, but it cannot remove the work of collecting accurate information unless the product specifically supports that workflow in your situation.
The average rating of 3.3 suggests that some users encounter friction, and my experience explains why that can happen. The app’s usefulness rises and falls with consistency. Missed entries create gaps, and gaps weaken the conclusions you draw from the reports or summaries you rely on. Someone who wants a passive system may become frustrated quickly, while someone who enjoys a short daily check may find the same requirement motivating.
There is also a trade-off between detail and speed. Recording every small transaction can produce a clearer picture, but it can also make the routine feel like unpaid administration. On the other hand, entering only large purchases may be fast but hide the small repeated expenses that often cause a budget to drift. I would choose a level of detail that supports one specific goal, then increase it only if the first version fails to answer an important question.
Do not use a budget entry as the only safeguard against missed payments. A tracker can help you plan, but it should not replace a bank alert, calendar reminder, or direct confirmation for a time-sensitive bill. Likewise, if you are dealing with debt, taxes, business accounts, or shared finances with complex rules, you may need a specialized tool or professional guidance. Dollarwise can organize awareness, but it is not a complete financial control system.
The age rating is Everyone, which makes the app broadly approachable from a content perspective. That does not mean every financial situation is equally suitable for it. A young user learning to separate needs from wants may benefit from the straightforward tracking habit. A person managing multiple accounts, irregular income, or detailed investments may outgrow the basic approach and need stronger automation or reporting.
Device compatibility is also worth checking before making it part of a long-term routine. The listed minimum is Android 7.0, and the current version is 6.4.0. If you use an older Android device, confirm that it can run the app comfortably and that your day-to-day entry process feels responsive. A finance habit is fragile when opening the app or finding the right screen becomes annoying.
Who should use it, and who should choose something else?
I would recommend Dollarwise to someone who wants a clear, active relationship with everyday spending. It suits a person who is willing to enter transactions, review categories, and make small adjustments instead of searching for a fully automatic answer. It can also work well for a short financial reset: track carefully for a few weeks, identify the main leaks, and decide which habits deserve attention.
It is less suitable for a user who rarely remembers manual tasks or wants all accounts consolidated without effort. It is also a questionable choice if the main need is investment performance, business bookkeeping, or a detailed shared-finance system. In those cases, a specialized alternative may justify its extra complexity because it addresses the actual problem rather than asking a simple tracker to do too much.
The free price makes experimentation easy, but I would still avoid treating cost as the main reason to choose it. The real question is whether the app’s workflow is comfortable enough to repeat. The in-app purchase range means I would be cautious about paying before I understand the free experience and the exact benefit of any optional purchase. For a budgeting tool, sustained use matters more than a long feature list.
HammerMedia has positioned this as a finance app centered on rewriting the user’s relationship with money, and I think that idea works best when interpreted practically. The app cannot change spending by itself. What it can do is give repeated choices a visible shape, provided I keep the record honest and review it with a specific question in mind.
After using it, my strongest advice is to create a small routine before exploring every possible option. Set up categories that match your real decisions, check dates carefully, record purchases close to the moment they happen, and reserve one weekly session for corrections. Those four habits do more for accuracy than an elaborate setup that you abandon after a few days.
My final view is cautiously positive. Dollarwise is most effective as a hands-on budgeting companion, not as a replacement for your bank or a fully automated financial platform. If you want to understand where everyday money goes and are prepared to participate in that process, it offers a sensible starting point. If you want the app to do the tracking for you, or your finances require advanced account management, I would look elsewhere. For the right user, its simplicity is useful; for the wrong one, that same simplicity becomes the main limitation.
Pros
- Clear spending categories make it easy to see where your money goes.
- Custom budgets help you set limits for specific expenses.
- Recurring transaction support reduces repetitive manual entries.
- Useful summaries can help identify spending patterns over time.
- A simple layout makes the app approachable for budgeting beginners.
Cons
- Some advanced tracking tools may require a paid subscription.
- Manual transaction entry can become time-consuming for frequent purchases.
- Budget accuracy depends on consistently recording every expense.
- Limited customization may not suit complex household finances.
- Users may need to verify how securely financial data is stored.
FAQs for Dollarwise: Budget & Tracking
What is Dollarwise: Budget & Tracking used for?
Dollarwise: Budget & Tracking is designed to help users organize their personal finances in one place. You can record income and expenses, categorize transactions, monitor spending habits, and compare your progress with a budget. It is useful for people who want a clearer view of where their money goes, although the quality of your results depends on entering accurate and consistent information.
Does Dollarwise connect directly to my bank accounts?
The availability of bank synchronization may depend on the app version, region, and supported financial institutions. Before relying on automatic imports, check the current app description and permission requests in the Google Play Store or App Store. If direct connections are unavailable, you may need to add transactions manually. Avoid sharing banking credentials unless the connection is provided through a trusted, clearly explained financial service.
Is Dollarwise: Budget & Tracking free to download and use?
Dollarwise may offer a free download with certain features available at no cost, while advanced tools could require a subscription, one-time purchase, or in-app payment. Pricing and included features can change, so review the store listing before downloading. Pay particular attention to trial periods, renewal terms, and whether deleting the app automatically cancels a subscription, since it usually does not.
Can I use Dollarwise to manage shared or multiple budgets?
The app can be useful for tracking different spending categories and financial goals, but support for multiple budgets, household sharing, or separate accounts depends on the available feature set. If you plan to manage finances with a partner or family member, verify whether the app includes synchronization or shared access. Otherwise, each person may need to maintain a separate record and update it manually.
Is my financial information safe when using Dollarwise?
Before entering sensitive financial details, review Dollarwise’s privacy policy, data-safety disclosures, and requested permissions. Budget information can reveal personal habits even when bank credentials are not involved. Use a strong device passcode, keep the app updated, and avoid recording unnecessary account details. Dollarwise should be treated as a budgeting tool, not as a replacement for your bank’s security controls or professional financial advice.

Dollarwise: Budget & Tracking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@dollarwise.com, visit https://dollarwise.app, or review their https://calebhammer.com/privacy-policy-dollarwise.










